


Inflation, conflict in the Middle East, and rising freight costs would normally weigh on industrial real estate demand.
Yet leasing activity across the Northeast industrial market is on pace for its strongest year since 2021, according to JLL’s Q2 2026 Northeast Industrial report.
More than 80 million square feet of active tenant requirements are currently searching for space across the region, while vacancy has held at just 5.9% for the past 15 months, well below many other major U.S. industrial markets.
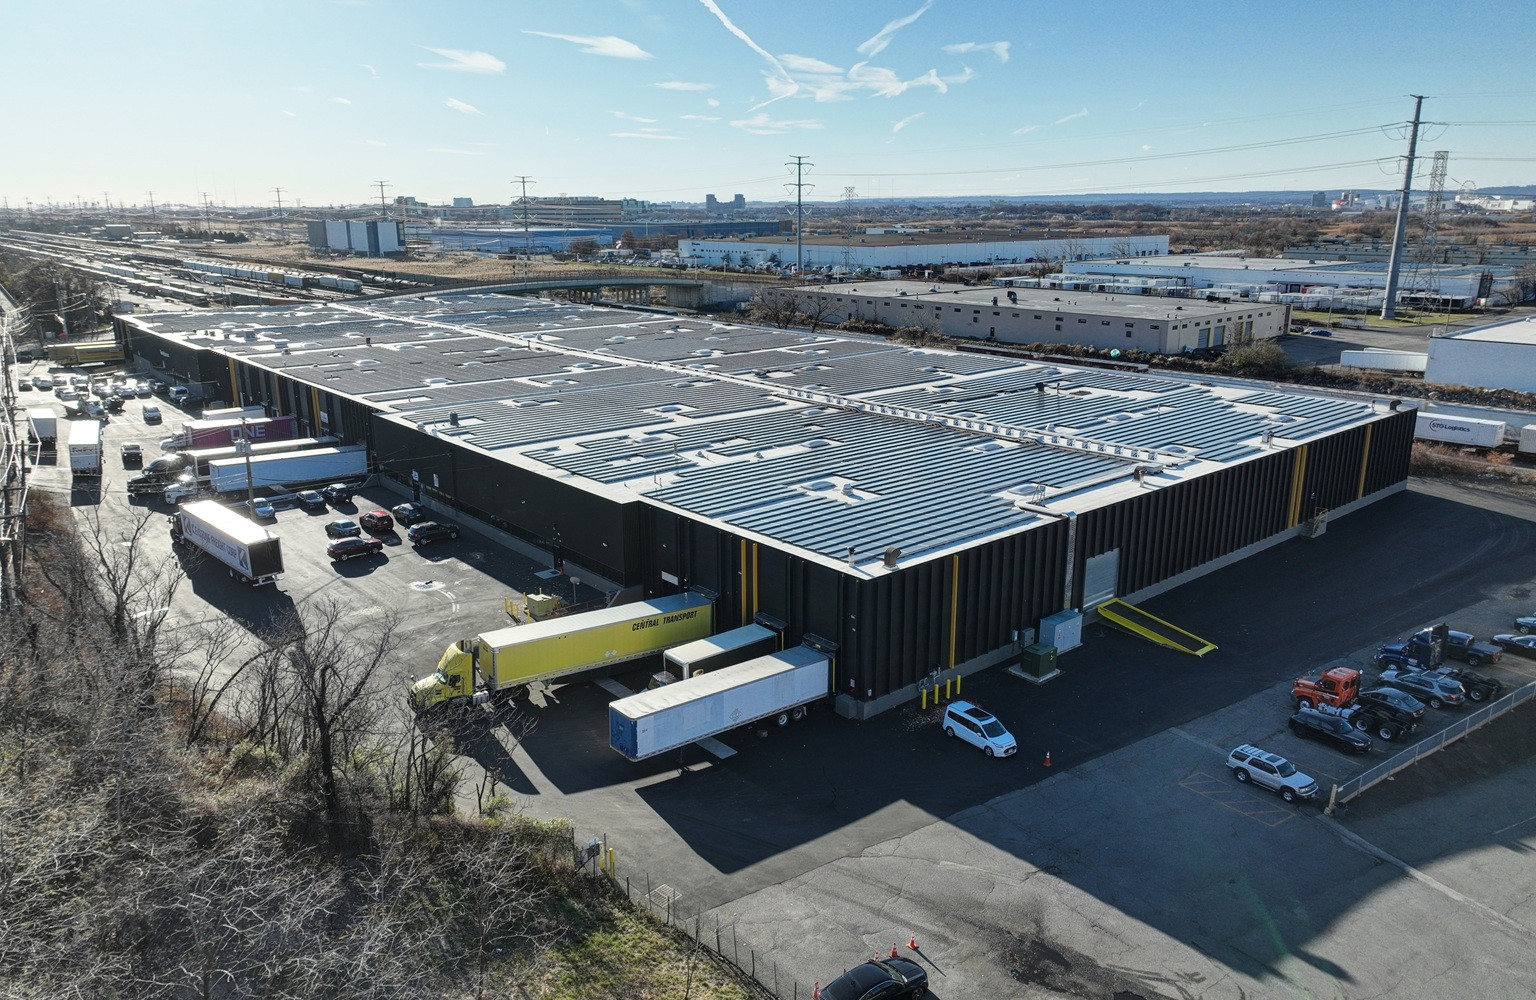
The New Jersey industrial market in Q2 2026 remains one of the strongest in the Northeast, with leasing activity and tenant demand driving robust fundamentals.
Northern New Jersey More Active
Northern New Jersey recorded nearly 398 million square feet of inventory, with net absorption of 3.6 million square feet year-to-date, vacancy at 5.0 percent, and availability at 8.2 percent, while Central New Jersey posted 341 million square feet of inventory, net absorption of 4.7 million square feet, vacancy at 5.5 percent, and availability at 10.3 percent.
Southern New Jersey, though smaller at 99.9 million square feet, added 747,798 square feet of net absorption, with vacancy at 9.9 percent and availability at 13.0 percent, according to JLL’s Northeast Industrial Outlook Report Q2 2026.
“The headlines continue to focus on inflation, geopolitical conflict and rising transportation costs, but companies still need resilient supply chains,” Rob Kossar, Vice Chairman and Head of JLL’s Northeast Industrial Region, said.
“That’s why we’re seeing occupiers make long-term real estate decisions instead of waiting for perfect economic conditions. Businesses are prioritizing network efficiency, modern facilities and proximity to consumers, and those factors continue to support healthy demand across the Northeast despite the uncertainty.”
Kossar said that what’s particularly notable is that companies aren’t sitting on the sidelines waiting for uncertainty to clear.
“There has been a noticeable increase in large leasing requirements from investment-grade tenants, while continued expansion by Chinese third-party logistics providers and e-commerce users is creating another important source of demand across the region.”
Rental Rates Divided by Submarkets, Asset Classes
Rental rates highlight the divide between submarkets and asset classes, with Northern New Jersey Class A asking rents averaging $21.38 per square foot compared to $15.95 for Class B/C, Central New Jersey Class A rents at $16.20 versus $13.94 for Class B/C, and Southern New Jersey remaining more affordable at $11.93 for Class A and $10.40 for Class B/C.
Construction activity has been concentrated in Central New Jersey, with 4.8 million square feet under construction, compared to 1.8 million in Northern New Jersey and just 264,000 in Southern New Jersey.
Capital markets activity has been strong, with notable transactions such as the sale of 100-140 Lincoln Highway in Kearny for $68.8 million at a 5.25 percent cap rate and 1065 Cranbury South River Road in Monroe for $139.6 million at a 5.10 percent cap rate.
Investor appetite remains robust for stabilized core product and value-add opportunities, supported by a wide lender pool and significant dry powder.
Looking ahead, tenant demand is expected to remain elevated, rents are projected to stay stable with pockets of upward pressure, and New Jersey’s limited pipeline could encourage developers to re-engage, keeping the market tight as leasing momentum drives vacancy lower and capital markets reinforce confidence in long-term fundamentals.
Blake Chroman, Principal of Sitex Group, a New Jersey-based real estate private equity firm focused on industrial assets, points back to the wave of speculative Class A development delivered in 2023 and 2024. Much of that construction was conceived when industrial vacancy fell to extremely low levels during COVID, and much of the new product arrived around the same time with similar configurations (e.g., 300,000–400,000 SF with single-side loading).
It took the market a few years to work through that supply, but Chroman says that’s happening now. Tenants have also become more sophisticated in how they use their space, including greater use of technology and automation, while competitive economics on newer buildings have made it easier for some users to trade up.
JLL’s Q2 data supports the shift: Class A accounted for 60.7% of new leasing in New Jersey, with Class A vacancy tightening quickly, particularly in larger size ranges.
The knock-on effect is being felt in Class B and C space, where vacancy has inched higher even in good infill locations. Chroman says owners are responding in a number of ways: offering more creative lease structures and incentive packages; dividing larger spaces to reach more tenants; investing in electrical capacity, HVAC, loading and fire/life safety systems; and looking closely at property taxes and operating expenses to bring down tenants’ overall occupancy costs.
“New Jersey industrial has demonstrated increasing momentum, but the divide between Class A and Class B space is growing. We had a tremendous amount of Class A product hit the market at roughly the same time, and it has taken a few years to absorb it. Now we’re seeing Class A vacancy come down quickly, in part because tenants have become more sophisticated about how they use their space and because the economics have made it possible for some of them to trade up,” Chroman said.
“That has put pressure on Class B and C owners, but it doesn’t mean those buildings are obsolete. Owners are getting much more creative, whether that means dividing space, structuring rents differently, upgrading power, HVAC and loading, or finding ways to lower operating costs. The bottom line is that owners of Class B and C space who can move quickly and creatively to meet the market will be successful in re-stabilizing their properties for the next five to 10 years.”


