


Inflation, conflict in the Middle East, and rising freight costs would normally weigh on industrial real estate demand.
Yet leasing activity across the Northeast industrial market is on pace for its strongest year since 2021, according to JLL’s Q2 2026 Northeast Industrial report.
More than 80 million square feet of active tenant requirements are currently searching for space across the region, while vacancy has held at just 5.9% for the past 15 months, well below many other major U.S. industrial markets.
The New Jersey industrial market in Q2 2026 remains one of the strongest in the Northeast, with leasing activity and tenant demand driving robust fundamentals.
Northern New Jersey More Active
Northern New Jersey recorded nearly 398 million square feet of inventory, with net absorption of 3.6 million square feet year-to-date, vacancy at 5.0 percent, and availability at 8.2 percent, while Central New Jersey posted 341 million square feet of inventory, net absorption of 4.7 million square feet, vacancy at 5.5 percent, and availability at 10.3 percent.
Southern New Jersey, though smaller at 99.9 million square feet, added 747,798 square feet of net absorption, with vacancy at 9.9 percent and availability at 13.0 percent, according to JLL’s Northeast Industrial Outlook Report Q2 2026.
“The headlines continue to focus on inflation, geopolitical conflict and rising transportation costs, but companies still need resilient supply chains,” Rob Kossar, Vice Chairman and Head of JLL’s Northeast Industrial Region, said.
“That’s why we’re seeing occupiers make long-term real estate decisions instead of waiting for perfect economic conditions. Businesses are prioritizing network efficiency, modern facilities and proximity to consumers, and those factors continue to support healthy demand across the Northeast despite the uncertainty.”
Kossar said that what’s particularly notable is that companies aren’t sitting on the sidelines waiting for uncertainty to clear.
“There has been a noticeable increase in large leasing requirements from investment-grade tenants, while continued expansion by Chinese third-party logistics providers and e-commerce users is creating another important source of demand across the region.”
Rental Rates Divided by Submarkets, Asset Classes
Rental rates highlight the divide between submarkets and asset classes, with Northern New Jersey Class A asking rents averaging $21.38 per square foot compared to $15.95 for Class B/C, Central New Jersey Class A rents at $16.20 versus $13.94 for Class B/C, and Southern New Jersey remaining more affordable at $11.93 for Class A and $10.40 for Class B/C.
Construction activity has been concentrated in Central New Jersey, with 4.8 million square feet under construction, compared to 1.8 million in Northern New Jersey and just 264,000 in Southern New Jersey.
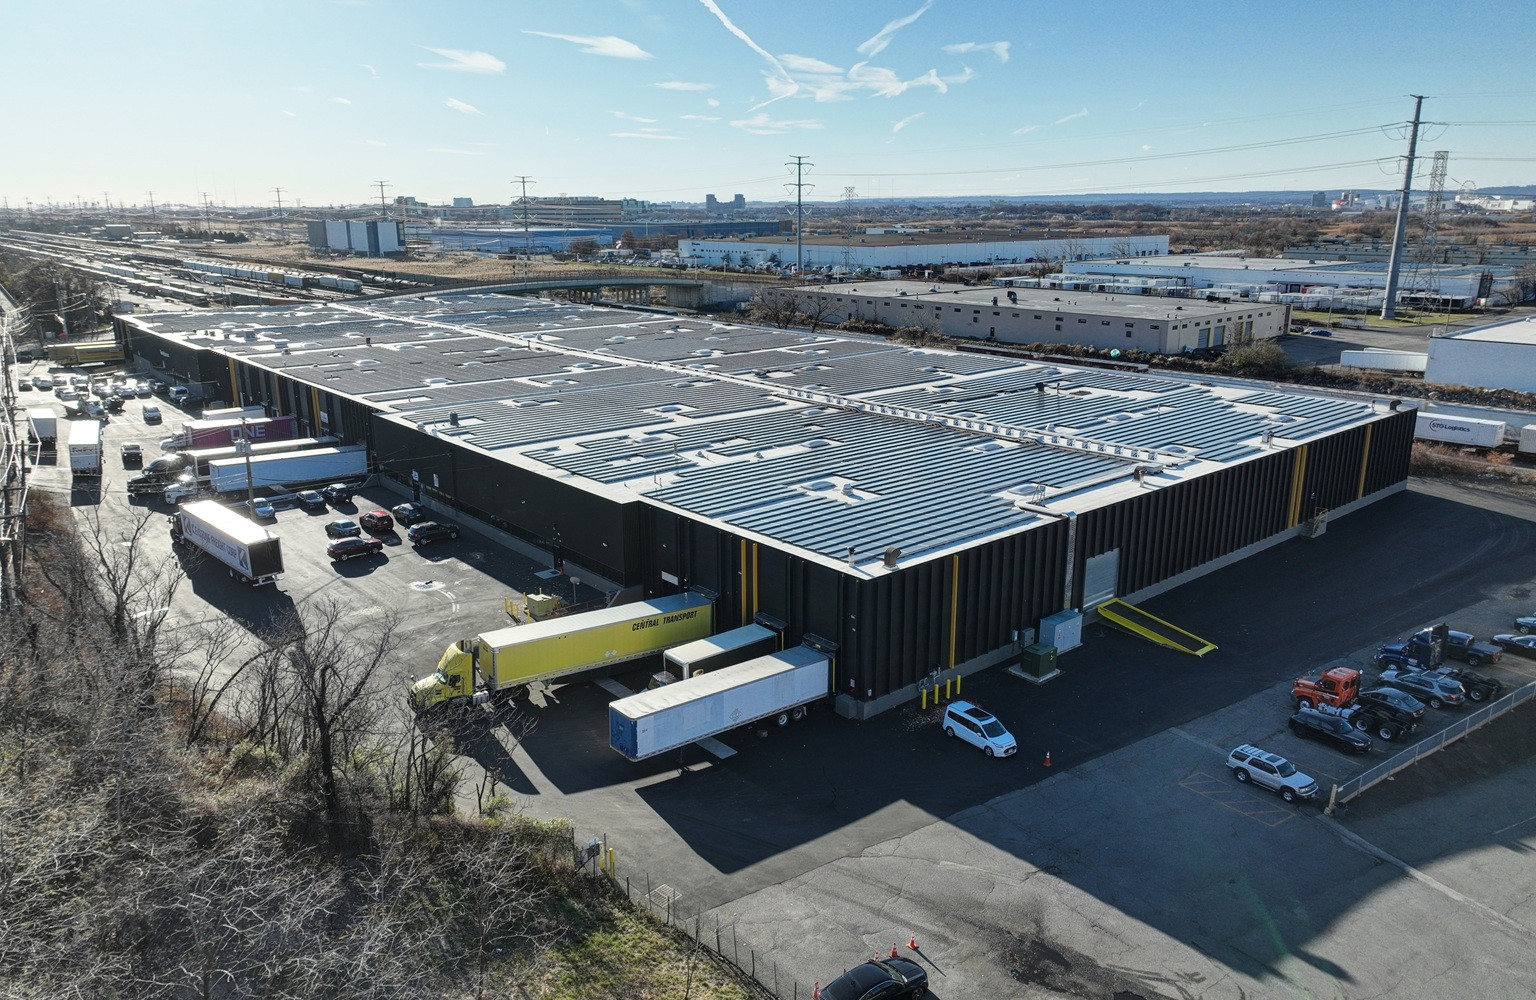
Capital markets activity has been strong, with notable transactions such as the sale of 100-140 Lincoln Highway in Kearny for $68.8 million at a 5.25 percent cap rate and 1065 Cranbury South River Road in Monroe for $139.6 million at a 5.10 percent cap rate.
Investor appetite remains robust for stabilized core product and value-add opportunities, supported by a wide lender pool and significant dry powder.
Looking ahead, tenant demand is expected to remain elevated, rents are projected to stay stable with pockets of upward pressure, and New Jersey’s limited pipeline could encourage developers to re-engage, keeping the market tight as leasing momentum drives vacancy lower and capital markets reinforce confidence in long-term fundamentals.


